Who Pays for Europe’s Rearmament When French Bond Yields Rise?
By the Factrail desk · Method: how we source and score · Last reviewed
TL;DR
Bond investors, defence contractors and fiscally stronger European governments stand to gain leverage as France’s borrowing costs rise and Europe tries to finance rearmament.
Article
The bill arrives before the decision
Bond investors, defence contractors and fiscally stronger European governments stand to gain leverage as France’s borrowing costs rise and Europe tries to finance rearmament. French taxpayers, households refinancing mortgages, local authorities and public-service users face the more immediate risk: a government paying a larger interest bill has less room to spend elsewhere. Italy is exposed through the same eurozone financing system, but its risk premium and fiscal profile are not interchangeable with France’s. The European Central Bank can contain disorderly financial fragmentation, yet it cannot erase the budget choices elected governments make. As of the morning of 29 October 2026, the ECB’s scheduled policy announcement has not occurred; treating a widely expected hold as an accomplished decision would obscure what investors actually know. The relevant decision is how the central bank weighs inflation driven by imported energy against sovereign financing stress, and whether Europe can protect both security and living standards without pretending that either has no price.
A monetary meeting under fiscal pressure
The ECB's scheduled announcement at 14:15 Central European Time on 29 October comes after two increases in its deposit rate since June, bringing it to 2.50% effective 16 September. The ECB’s September communication acknowledged a Middle East energy shock and forecast inflation above target. A Reuters preview published ahead of the meeting says the central bank is widely expected to hold on 29 October, while traders price the prospect of subsequent tightening. That is a forecast, not the result. Monetary policy is aimed at euro-area price stability, not at making French debt inexpensive. Yet a central bank cannot disregard financial transmission: rate rises affect bank loans, bond yields and public debt service, while abruptly widening national borrowing premiums can make the same policy much harsher in one member state than another. The challenge is to distinguish a warranted market repricing of fiscal risk from a self-reinforcing episode in which liquidity disappears and financial markets cease to function normally. Those are different problems and justify different responses. A hold might avoid adding an immediate rate shock, but it would not automatically reverse the premium investors require to hold French government bonds.
Why the France-Germany spread matters
A sovereign spread is the yield difference between two debts of comparable maturity, often the French ten-year OAT and German Bund. Investors use the Bund as a euro-denominated reference. A wider French spread means France must offer additional compensation, even if the general euro interest-rate level has not changed. The mechanism matters more than the daily headline. New bond issues refinance maturing debt at prevailing rates. France does not suddenly pay today’s market yield on its entire existing fixed-rate stock, so a one-day move must not be multiplied by all outstanding debt and presented as an immediate budget loss. Exposure accumulates as government securities roll over and deficits require fresh issuance. Higher yields can also affect collateral values, banks, insurers and corporate credit pricing. The consequences propagate to households through lending margins and to local governments through financing conditions. Because France is a large eurozone issuer, stress can spill across portfolios. Investors may sell French paper and rotate toward German securities, making the relative yield difference look even more dramatic. The spread is a price signal, not proof of national insolvency, and a headline high yield does not demonstrate that a rescue is required.
Italy is a comparator, not a duplicate
Italy has long offered a useful test of how euro members are treated when investors worry about debt stocks, fiscal growth and political commitments. But France’s newer bond-market discomfort does not mean Italy automatically loses market access or that one government’s policies caused every movement in another country's yield. Each country differs in its debt maturity, primary budget position, domestic savings, pension-fund demand and credibility of fiscal plans. There is also a distinction between the Italy-Germany spread narrowing because Italian risk declines and narrowing because German yields rise. Investors should examine both the premium and the absolute funding cost. A period when France’s premium rises toward Italian levels may reorder a familiar market hierarchy without establishing that Italian finances improved. European banks holding cross-border government debt can transmit the repricing. A risk premium borne in one country can therefore raise financing pressure elsewhere, even absent a fresh national scandal. The important political question is whether governments respond by publishing believable multiyear budgets, or by hoping central-bank language will substitute for difficult choices. The latter delays the reckoning rather than removing it.
Rearmament creates winners before it creates safety
Europe’s defence requirements are real: stockpiles must be replenished, air defences expanded, and industrial capacity restored after years of underinvestment. Equipment producers, subcontractors, factories and workers can benefit from the new orders. Taxpayers can also benefit if spending credibly deters attack and reduces future insecurity. But procurement decisions decide who receives cash, where jobs are created, how much output is delivered and whether contracts are competitive. A government can announce a large programme without disbursing its full headline number. Commitments, authorisations, contracts and paid invoices are different stages. Funding plans that rely on national borrowing create a second beneficiary group: bondholders receive interest, while voters service the debt. If expensive borrowing is paired with sluggish productivity, defence purchases can crowd out investment in infrastructure and public services. Conversely, if better-coordinated procurement reduces duplication and brings production onshore, some of the expense supports jobs and technological capability. The balance depends on contracts and implementation, not slogans about strategic autonomy. Defence supply cannot be judged by the size of a promised budget alone.
The invisible contest over public services
The incidence of more expensive borrowing is political rather than automatic. A government could raise taxes, slow new spending, defer capital projects, compress welfare programmes or accept a higher deficit. The same headline fiscal gap creates different winners and losers depending on that choice. A tax increase concentrated on high incomes has a different distributional profile from a rise in consumption taxes. Freezing social benefits in a period of inflation lowers their real value even without an explicit nominal cut. Postponing rail maintenance transfers costs to future users. Cutting school capital budgets makes poorer communities bear a delayed price. Defence projects are similarly uneven geographically: one region may gain skilled manufacturing jobs while another experiences fewer hospital appointments or worse municipal services. An intellectually serious analysis cannot attribute every future welfare change to the 29 October ECB meeting. It can identify the pathways through which tighter financial conditions constrain the choices that ministries and parliaments later make. The first measurable signs are debt-auction costs, the budget’s interest-service line, enacted appropriations and real per-capita service spending.
How the ECB can and cannot intervene
The ECB’s Transmission Protection Instrument was designed to address unwarranted, disorderly market dynamics threatening monetary-policy transmission, subject to conditions. It is not a general promise to purchase any government’s bonds whenever its budget becomes politically uncomfortable. The bank must consider fiscal sustainability, macroeconomic policies and compliance with the European fiscal framework. By contrast, ordinary policy operations, balance-sheet reinvestment choices and standard refinancing terms can affect liquidity without directly underwriting national budgets. That institutional distinction is essential for public accountability. A government that advocates higher military spending must identify how it will finance that choice under plausible interest-rate scenarios. Asking the ECB to protect the euro area from fragmentation is not the same as asking it to fund parliamentary commitments. If the central bank intervenes too readily, markets can infer that political risk will always be socialised. If it stands aside during a genuine liquidity spiral, stress may make monetary policy uneven and hurt households who did not cause the fiscal problem. Independence is valuable precisely because both risks exist.
An oil shock complicates the trade-off
The 2026 energy-price shock described in the ECB’s September assessment creates a dilemma unlike a simple demand boom. Higher imported energy costs can raise consumer prices and reduce the money households have for other goods at the same time. Raising policy rates cannot manufacture more oil. It can, however, help keep temporary inflation from feeding into persistent wage-price dynamics and future inflation expectations. That protection is important for pensioners and lower-income consumers, whose savings and earnings are vulnerable to inflation. Yet higher rates also make borrowing for homes, businesses and governments costlier. The ECB must assess persistence and the transmission of the shock, not just an isolated inflation figure. The burden of adjustment can be shifted to national fiscal policy through targeted, transparent assistance rather than broad untargeted subsidies. Those policies have their own budget costs. In a defence build-up, the temptation to promise cheap energy, larger military budgets and unchanged public services simultaneously is especially strong. The bond market eventually asks which pledge is funded. Those questions are political even when a central-bank meeting makes them urgent.
The beneficiary map
There is no single conspiracy behind wider bond spreads. German sovereign borrowers can gain relative haven demand, although falling Bund yields are not guaranteed and can change quickly. Large institutional investors may obtain higher prospective yields on new French securities, but holders of existing bonds can suffer mark-to-market losses. Defence firms can receive new contracts, but their shareholders do not necessarily gain if costs or execution failures consume margins. French and Italian governments may gain additional security capacity, but elected officials face greater pressure to justify the spending. Households with variable-rate or newly refinanced loans confront higher debt-service costs where local lending conditions tighten; those with fixed borrowing may be insulated until refinancing. Public workers and benefit recipients could face austerity if officials choose them as the adjustment margin. Such outcomes are conditional, not observed consequences of a meeting that has yet to announce its decision. The test for claims about winners must therefore combine contracts, actual bond issuance, tax changes and measurable household outcomes rather than infer all effects from market prices alone.
What readers should watch after Frankfurt
First, record the exact 29 October ECB decision and the language used to distinguish imported inflation from domestic persistence. Second, compare French and Italian ten-year yields and their spreads against Germany over multiple trading days, not one volatile quote. Third, inspect national debt-agency issuance calendars: refinancing volume determines how quickly yield changes feed into budgets. Fourth, audit European defence proposals by legal status, purchasing authority, supplier and cash-disbursement timetable. Fifth, compare government interest expenditure against health, housing, education and infrastructure appropriations in both nominal and inflation-adjusted terms. Sixth, demand publication of procurement milestones and performance, because an expensive weapon delivered late is neither a fiscal saving nor a defence success. A final test concerns the ECB’s boundary: the institution can preserve consistent monetary transmission while refusing to turn a member state's political promises into an unconditional monetary guarantee. The exact outcome remains open, but voters should not be required to discover the cost only when a school, hospital or household budget absorbs it.
Welfare indicators and attribution
Monitor inflation-adjusted disposable household income, mortgage-payment-to-income ratios for new borrowers, tax burden by income decile, health and education expenditure per person, unemployment in defence-manufacturing regions, sovereign interest expense as a share of revenue and defence procurement delivered against contracted milestones. For each series establish baseline, country, date and a defensible comparator; none is an automatic moral score for an individual politician. A French yield premium is a financial driver, not itself evidence that household poverty increased. Procurement contracts may directly affect output while their welfare value depends on security outcomes and opportunity cost. The relevant Factrail causal sequence runs from a named actor’s documented budget decision through the financing or procurement mechanism to observed changes in a welfare indicator. At present, the 29 October policy decision is pending and many downstream indicators have not been observed. Treat projections as scenarios, identify alternative explanations, and do not fabricate a numerical rating or causation coefficient.
Sources and methodology
ECB monetary policy press conference schedule and rates (opens in a new tab); ECB September 2026 monetary-policy statement (opens in a new tab); Reuters ECB meeting preview, 29 October 2026 (opens in a new tab); ING October ECB scenario analysis, 27 October 2026 (opens in a new tab); ECB headquarters and institutional background (opens in a new tab); ECB policy rates chronology (opens in a new tab). Related Factrail coverage to verify before publication: French bond stress article, ECB rate watch, European banking decision. These internal URLs are candidate paths requiring a successful live-site response before the CMS enables them.
Evidence
The sources this article cites, claim-bearing material first.
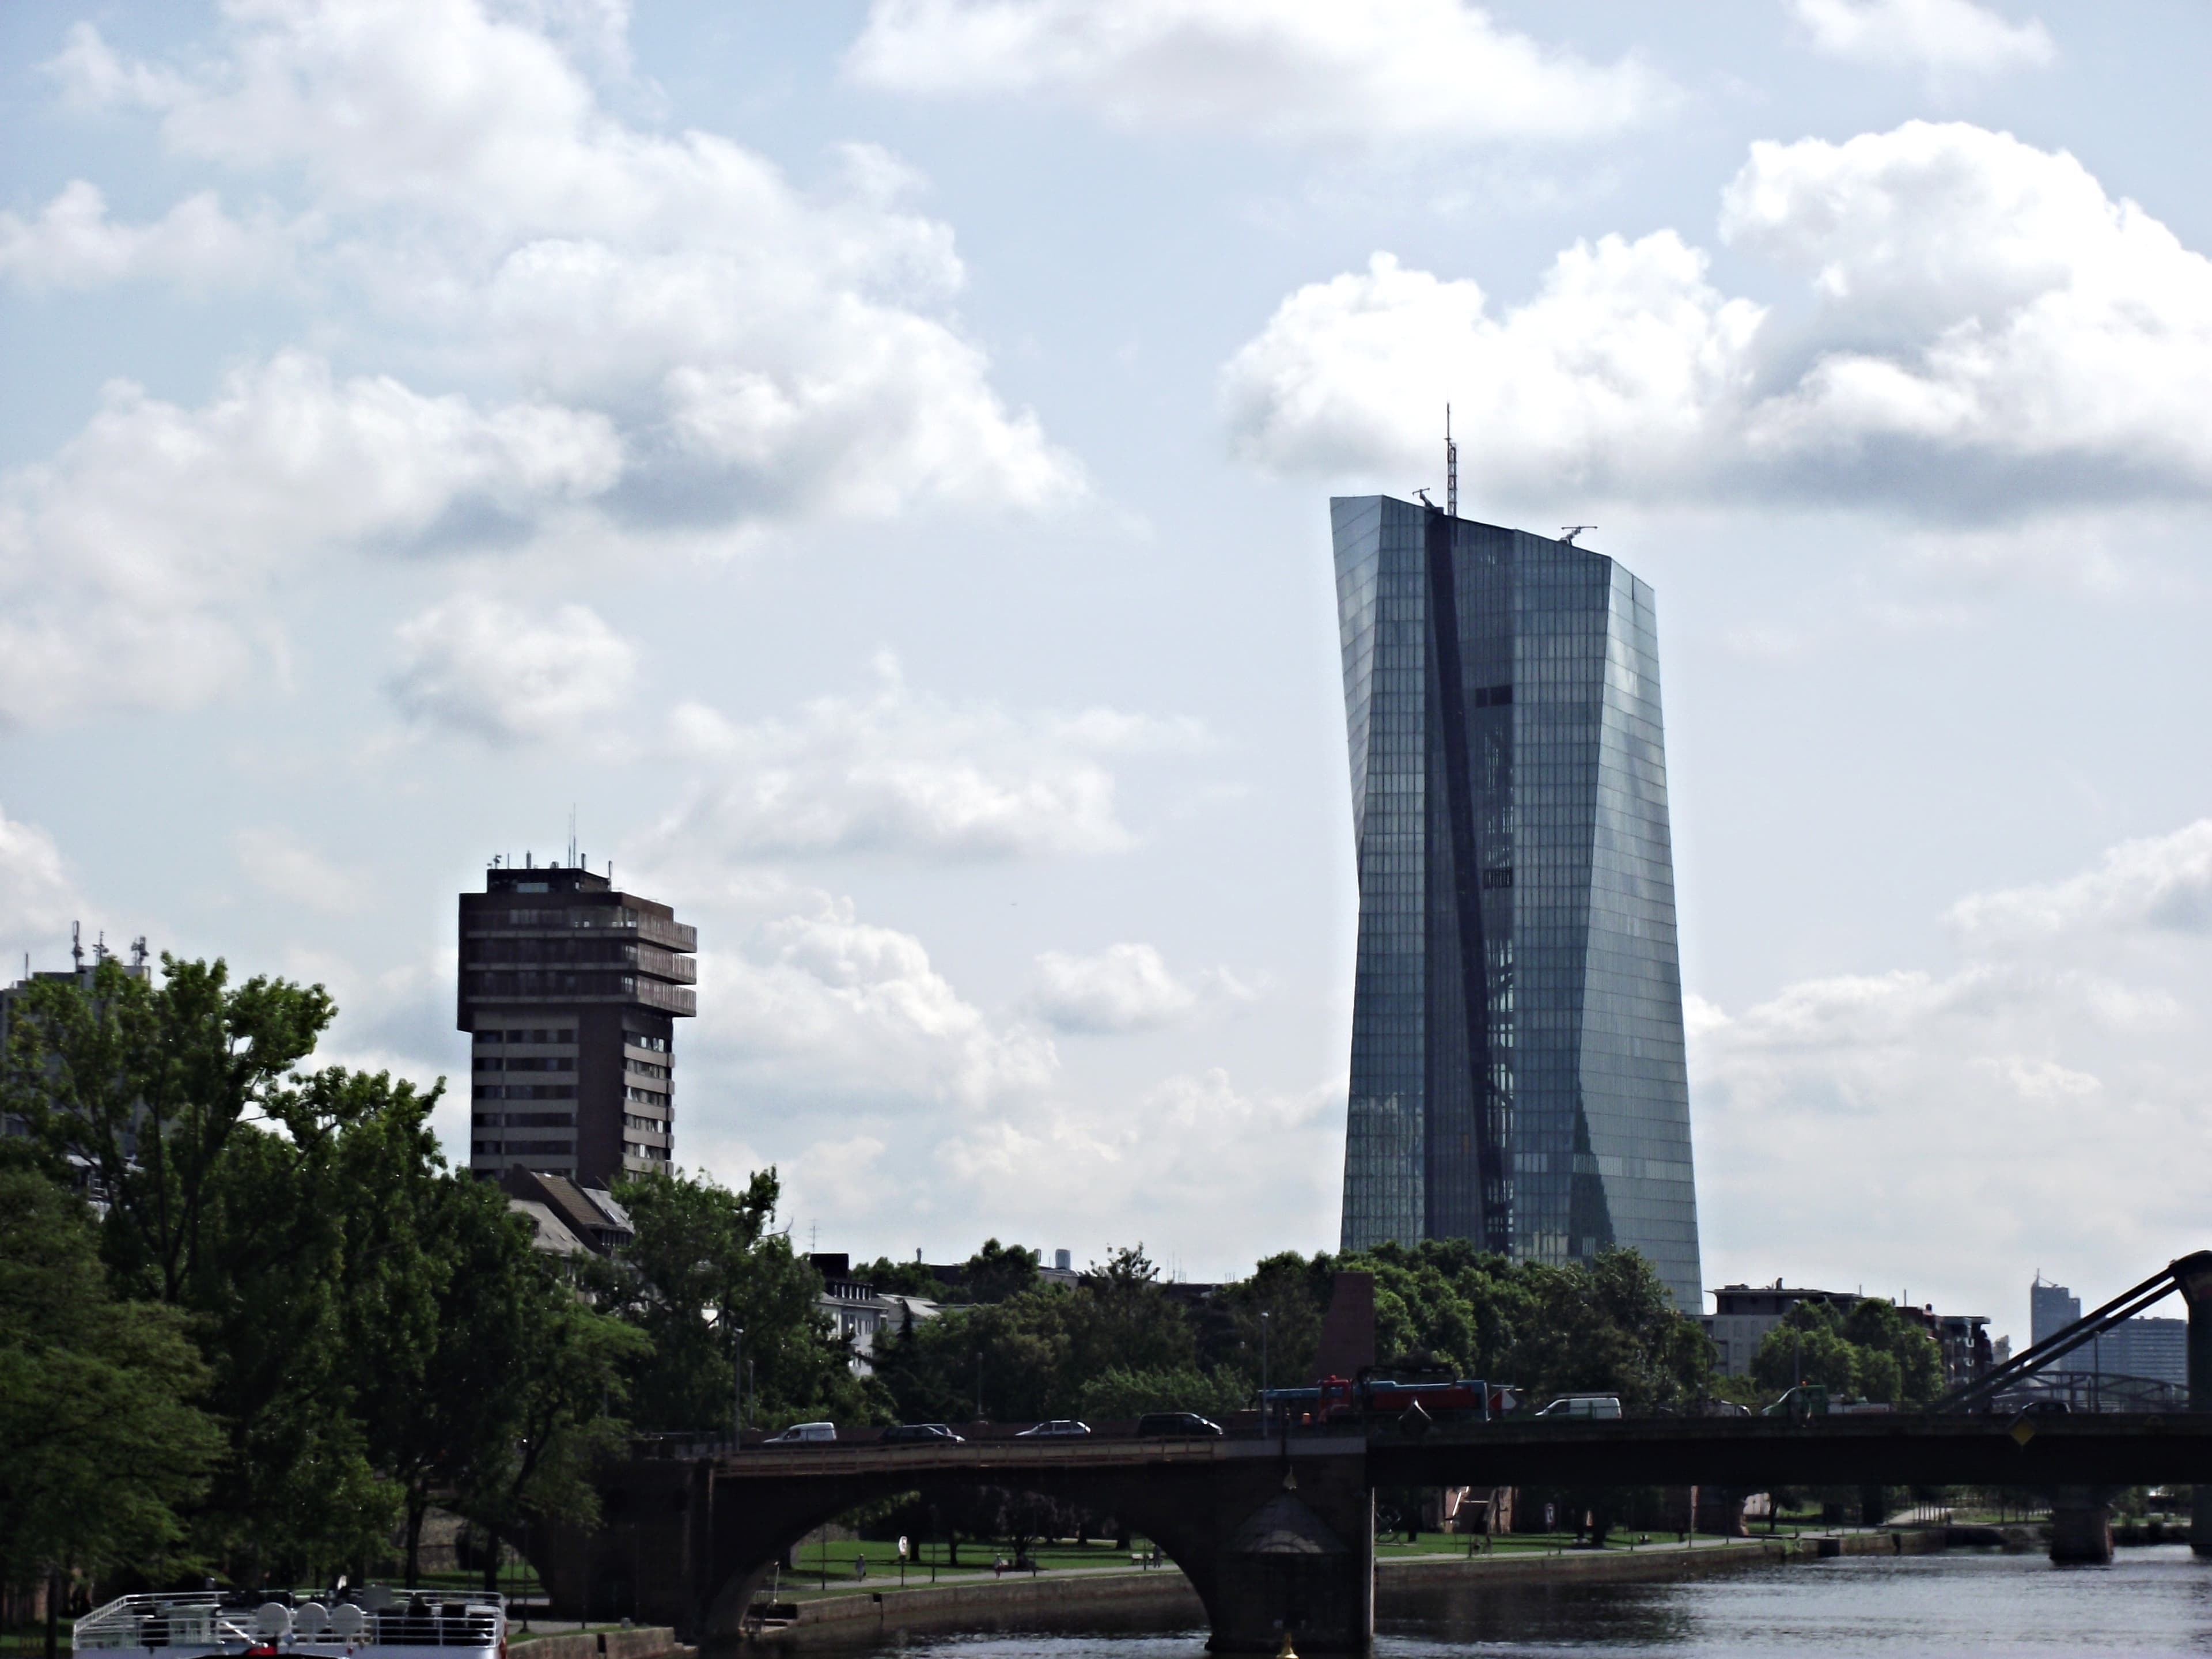
- ecb.europa.eu · ecb.europa.eu/ecb-and-you/visits/premises/html/index.en.html