Reserve Bank of Australia: Who Sets Rates, Who Pays?
PROVEN: The Reserve Bank of Australia exercises enormous influence over the price of credit, but its governing bodies do not control the government's housing supply or individual banks' mortgage margins.
About
Verdict and human stakes
PROVEN: The Reserve Bank of Australia exercises enormous influence over the price of credit, but its governing bodies do not control the government's housing supply or individual banks' mortgage margins. A 1 March 2025 institutional reform divided monetary policy, payments oversight and corporate management among three boards. This made accountability more legible while leaving the Governor central to coordination. The strongest criticism is not that a rate decision is inherently illegitimate; it is that a nationwide rate can impose unusually heavy cash-flow pressure on recent variable-rate borrowers even when the policy is designed to restrain inflation that hurts everyone. Borrowers, depositors, savers, renters and firms experience that decision differently. The bank must explain its forecasts and mistakes, while elected governments remain responsible for taxation, zoning and social assistance.
The 2025 institutional change
The Reserve Bank Act framework was amended so that, from 1 March 2025, the old Reserve Bank Board ceased to be the single venue for both monetary decisions and corporate governance. The Monetary Policy Board now decides cash-rate and broader monetary policy; the Payments System Board oversees payments policy; the Governance Board manages the central bank's organizational operations, banknotes and transactional services. The separation is designed to prevent administrative priorities from dominating rate discussions. Michele Bullock, Governor since 18 September 2023, chairs all three boards, while Deputy Governor Andrew Hauser participates in the governance structure. That continuity can improve coordination but also raises a legitimate question: how independently can an administrative board scrutinize management when the Governor chairs it? The legislation assigns different powers, not three unrelated corporations.
Money on the balance sheet
At 30 June 2025 the RBA's assets were approximately A$404 billion, compared with A$414 billion a year earlier. The report attributes the decline chiefly to maturing domestic government securities. Its 2025 financial statements record about A$10.987 billion net profit, reversing the 2024 loss of A$4.153 billion, helped by securities and foreign-exchange gains. This is not A$11 billion in commercial profits to be distributed automatically to investors. The RBA is a statutory public institution; its financial assets back central-bank liabilities such as currency and bank reserves. Accounting income can be driven by mark-to-market movements and monetary operations rather than fees charged to consumers. The weekly October 2026 balance sheet was smaller again, around A$346.9 billion at 14 October. These stocks should not be added to annual income figures.
Policy power, veto and accountability
The Monetary Policy Board controls the policy rate and tools directed toward price stability and sustainable employment. Monetary policy is not a referendum on every household mortgage. The Governor communicates decisions, board members have legislated terms, and the Treasurer's office participates through public accountability channels rather than directly authoring each board vote. The Payments System Board can address card and payment infrastructure issues under a different mandate, while the Governance Board oversees service delivery and expenditure. There is a statutory mechanism for dealing with a serious disagreement between government and monetary authorities; treating the board as absolutely beyond public law would be wrong. Conversely, politicians cannot simply order it to conceal inflation data or write off private mortgages without legal authority.
Who benefits and who pays
Rising interest rates transfer pressure through borrowing costs, asset prices and expectations. A family who bought a home on a floating mortgage can face rapid repayment increases; an older depositor may receive higher interest income. Firms with short-term debt can delay hiring or expansion, while customers may benefit over time if slower demand prevents a persistent rise in goods prices. Yet poorer tenants can be hurt twice if landlords attempt to pass along financing costs and unemployment risk rises. No single interest-rate announcement proves the final incidence across social groups. To test equity, researchers should combine RBA credit statistics, Australian Bureau of Statistics household measures and lender disclosures. The apparent beneficiary of higher deposit rates might not receive the full increase if banks widen spreads.
Timeline and contested record
The Australian central bank began operating in its modern statutory form in 1960. During the pandemic period its balance sheet expanded dramatically through unconventional monetary support; later maturities reduced the bond portfolio. Bullock became Governor in September 2023. The new three-board governance framework began in March 2025. At the close of that financial year the bank held about A$404 billion in assets, with domestic market holdings still a large share. By October 2026 its public weekly statement reflected further normalization. This sequence matters when commentators blame the current board for every older bond position: many assets were acquired under a different policy environment. The new board inherits financial exposure and must explain how that exposure affects future financial statements.
The best defense and the unresolved test
The strongest counter-view holds that an independent central bank must sometimes restrict credit to prevent inflation expectations from becoming entrenched; avoiding a painful adjustment today can cause even greater losses of purchasing power later. That argument is economically serious, not a blanket exemption from scrutiny. Forecast errors, distributional burdens and delayed policy transmission require explanation even when the legal objective is defensible. The RBA cannot instantly create housing supply or reduce global energy prices, so fiscal and structural policy also determine outcomes. An investigator should compare each decision's published forecast with subsequent inflation, wage, labor-market and mortgage-arrears data. HYPOTHESIS: political favoritism or private capture explains an individual rate vote; no such finding follows from the bank's balance sheet.
What to watch and related coverage
Watch the next Monetary Policy Board minutes and the RBA's forecasts, distinguishing new information from revisions to assumptions. Track 2026–27 cash-rate decisions against ABS inflation and employment releases; track housing credit, arrears and the banks' published average loan rates. Scrutinize the first full financial cycles governed by the post-2025 board architecture. On Factrail, Inflationary Pressure (opens in a new tab) supplies the prices channel; Housing Affordability (opens in a new tab) shows who cannot access homes; Energy Security (opens in a new tab) explains shocks monetary policy cannot remedy by itself.
Related on Factrail
- Energy Security (opens in a new tab)
- Housing Affordability (opens in a new tab)
- Inflationary Pressure (opens in a new tab)
Sources
- Reserve Bank of Australia, Annual Report 2025 (2025-09) (opens in a new tab)
- Reserve Bank of Australia, Audited financial statements and management (2025-09) (opens in a new tab)
- Reserve Bank of Australia, Three-board structure from March 2025 (2026-10) (opens in a new tab)
- Reserve Bank of Australia, Monetary Policy Board authority (2026-10) (opens in a new tab)
- Reserve Bank of Australia, Statutory leadership and terms (2026-10) (opens in a new tab)
- Reserve Bank of Australia, Weekly central bank balance sheet (2026-10) (opens in a new tab)
Wikimedia Commons cover rights
- File: commons.wikimedia.org (opens in a new tab)
- Direct media: upload.wikimedia.org (opens in a new tab)
- Creator: Danausi
- License: Public domain
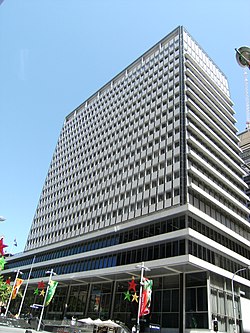
- Alt text: Reserve Bank of Australia head office building in Martin Place, Sydney
By the Factrail desk · Method: how we source and score · Last reviewed