Google's $500bn Wipeout Exposes the Real Cost of AI
By the Factrail desk · Method: how we source and score · Last reviewed
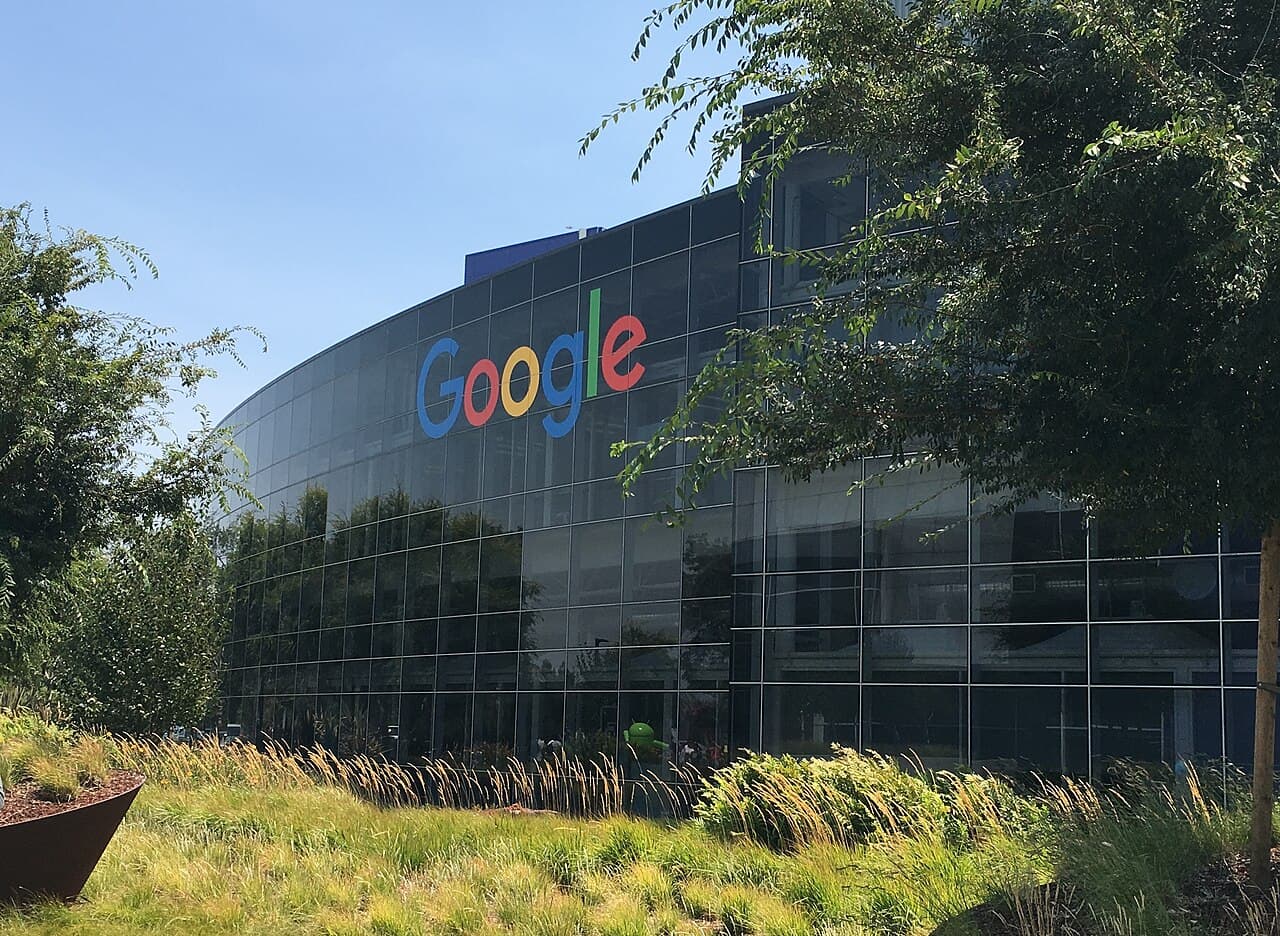
TL;DR
Alphabet's 29 October stock collapse exposed an uncomfortable division inside the AI boom: the companies receiving orders for chips, data-centre equipment and electricity can collect revenue today, while the owners of the company writing those cheques must wait to learn whether tomorrow's demand ...
Key graph impact
The article explains graph entities; the causal edges belong to the facts and drivers it links to.
- ArticleGoogle's $500bn Wipeout Exposes the Real Cost of AI
- mentionsDriverDigital Infrastructure Investment & Public Digitalization Programs
- strengthensIndicators (2)Internet Penetration (Individuals Using the Internet, % of Population) - World
- ArticleGoogle's $500bn Wipeout Exposes the Real Cost of AI
- mentionsDriverFrontier AI race / capability competition
- weakensIndicatorHaving a say in government
- ArticleGoogle's $500bn Wipeout Exposes the Real Cost of AI
- mentionsDriverConcentration of AI Compute Resources
- Better
Internet Penetration (Individuals Using the Internet, % of Population) - World
via Digital Infrastructure Investment & Public Digitalization Programs
Strengthens · 80% impact strength
Observed
73.6% of population · 26.4 below the normal line (2025)
Worse than normal8 readings, 2018–2025: rose from 49.4% of population to 73.6% of population.
Above normal = better · Lag ~12 mo
- Better
E-Government Development Index (EGDI) - Global Average
via Digital Infrastructure Investment & Public Digitalization Programs
Strengthens · 75% impact strength
Above normal = better · Lag ~18 mo
Weakens · 50% impact strength
Observed
29.8% of population aged 16-65 years · 8.13 below the normal line (2023)
Worse than normalTwo readings: 30.2% of population aged 16-65 years (2021) and 29.8% of population aged 16-65 years (2023).
20212023 Above normal = better · Lag ~3 mo
Article
00 Verdict
Alphabet's 29 October stock collapse exposed an uncomfortable division inside the AI boom: the companies receiving orders for chips, data-centre equipment and electricity can collect revenue today, while the owners of the company writing those cheques must wait to learn whether tomorrow's demand justifies the bill. Alphabet's third-quarter filing with the SEC (opens in a new tab) shows $42.29 billion of operating cash generation against $51.36 billion of property-and-equipment purchases, leaving free cash flow negative $9.065 billion. That is an investment shortfall, not an operating loss or evidence of insolvency. It is nonetheless a significant change in who finances the expansion.
Shares fell 12.6% on 29 October, their worst percentage day since the 2004 listing. Market-value estimates differ by methodology and closing-price conventions: Yahoo Finance's reconstruction (opens in a new tab) put the loss at roughly $475 billion, while Associated Press coverage (opens in a new tab) and other accounts described a loss approaching $500 billion. No equivalent sum was withdrawn from bank accounts; the number is the change in the market price of shares. It still matters to households owning broad equity funds, including American retirement accounts and internationally diversified British pensions.
The immediate beneficiaries of the spending are infrastructure sellers. The long-term beneficiaries might be cloud customers and society if the new capacity produces cheaper, more useful services. The exposed parties are shareholders funding the construction, and ultimately customers or workers if the economics force higher prices or restructuring. Those are possible channels, not established outcomes.
01 Hidden finding
The striking detail is not that Alphabet is spending heavily. It is that spending on fixed assets outran the cash generated by operations for the second consecutive quarter while the legacy advertising franchise showed slower-than-expected growth. The Reuters earnings account (opens in a new tab) says advertising revenue missed market expectations by about $1.4 billion. Search and related revenue grew 12% to $63.35 billion, so the business did not collapse; it simply failed to grow as quickly as investors had priced in.
There are two very different stories inside the same company. Google Cloud grew 103% to $30.71 billion. Google Services grew 11% to $96.30 billion. The former is growing into the capital expenditure; the latter remains the enormous engine needed to finance it. An investor paying for an AI-led future must now test both propositions together: that accelerated cloud sales can convert to cash, and that AI-powered search can defend the advertising model while changing the way users find information.
The balance sheet also prevents a melodramatic reading of negative quarterly free cash flow. The company's filed cash, cash equivalents and marketable securities were substantial, and trailing-twelve-month free cash flow remained positive at $19.75 billion. But declining near-term discretionary cash changes the cost of choices: reinvesting, reducing debt, paying shareholders and buying other businesses cannot all be treated as costless.
02 Who holds the levers
Alphabet and Google (opens in a new tab) management set the expenditure envelope. Chief executive Sundar Pichai (opens in a new tab) is responsible for explaining why the demand visible today warrants the capacity being built for later years. Chief financial officer Anat Ashkenazi told analysts, as reported by Reuters, that management expected 2027 capital expenditure to rise significantly above the company's 2026 guidance of $195 billion to $205 billion. That statement is a direction of travel, not a disclosed $300 billion budget; the latter figure appeared as an investor's hypothetical in the Reuters report.
Google Cloud chief Thomas Kurian must turn booked commitments into delivered, billable workloads with satisfactory margins. Chief business officer Philipp Schindler has the distinct problem of monetising AI Mode without damaging the search-ad unit. Reuters reported Schindler's explanation that greater AI Mode use contributed to the deceleration of search advertising growth, even as management argued AI features were expanding query activity. Those claims are compatible: more searches do not guarantee the same revenue per search.
External suppliers have different incentives. Nvidia (opens in a new tab) can benefit from demand for accelerators across the industry, although Google's proprietary tensor processing units also compete for AI workloads. Amazon (opens in a new tab) is simultaneously a rival in cloud computing and an illustration of the sector-wide capital race. Intel (opens in a new tab) faces its own demand and execution pressures; its stock reaction must not be presented as direct evidence of Alphabet's accounting condition. Public shareholders, creditors and directors are the governance counterweights, but outsiders do not set the company's quarterly infrastructure commitments.
03 Document trail
Start with the 28 October SEC earnings exhibit (opens in a new tab), rather than a share-price headline. It records quarterly revenue of $127.577 billion, operating income of $40.576 billion and net income available to common shareholders of $26.170 billion. It records property purchases of $51.355 billion and operating cash inflow of $42.290 billion. Those numbers produce the reported free-cash-flow deficit of $9.065 billion under Alphabet's disclosed definition. The prior quarter had a $5.855 billion deficit, while the comparable 2025 third quarter generated positive cash.
The same filing shows 12 million Class A shares issued for $4.3 billion and 24 million Class C shares for $8.1 billion in net proceeds under an at-the-market programme. Share issuance distributes ownership among more shares unless offset elsewhere; it must not be falsely described as a direct measure of the 29 October market loss. The company also issued senior unsecured notes for net proceeds of $28.7 billion during the quarter. These transactions demonstrate the availability and use of financing channels, not a cash emergency.
The Reuters earnings report (opens in a new tab) supplies the analysts' expectations and management's description of the search and cloud businesses. 9to5Google's earnings breakdown (opens in a new tab) independently summarises the published segment figures. AP's market report (opens in a new tab) supplies the wider index reaction. These are different forms of evidence: a company filing for audited-style financial reconciliation, journalism for investor and market reaction, and analytical inference for future consequences.
04 How it was done
The mechanics are unusually straightforward. Operating cash arrived from search, advertising, subscriptions, cloud services and other activities. Capital was committed to buildings, computing systems, networking and other long-lived assets. Because property purchases exceeded operating inflow, the company could not fund all this quarter's fixed-asset investment out of this quarter's operating cash. It therefore had to draw on other liquidity, financing or balance-sheet resources. That does not mean every dollar of borrowing or equity raised can be earmarked to a particular server rack.
The operational risk is a timing mismatch. Data-centre construction and semiconductor orders must often be planned well before a customer workload materialises. The reported Google Cloud backlog of $561 billion is significant evidence of prospective demand, according to Reuters, but backlog is not the same as cash received, and contractual obligations need not all translate to profit at the same rate or at the same time. Capacity utilisation, energy costs, depreciation, maintenance and price competition intervene between a signed order and durable shareholder returns.
The second mechanism is cannibalisation risk. An answer generated inside AI Mode may change how often a user clicks a conventional sponsored link, how ads are placed and how advertisers measure conversions. Alphabet can be successful at retaining users while producing a weaker advertising yield per query. Conversely, better AI search might create commercially valuable questions that never previously occurred. The Factrail analysis of AI's uneven productivity gains (opens in a new tab) provides a useful distinction between technological capability and measured economic output.
05 Money, access and intermediaries
The relevant AI race (opens in a new tab) is not merely a contest over model quality. It includes access to land, grid connections, transmission capacity, chips, cooling technology, specialist engineers and a distribution channel that can sell the resulting computing power. That is why the concentration of AI compute resources (opens in a new tab) matters. Companies already able to finance enormous clusters can strengthen their position even if the near-term economics are uncomfortable for their shareholders.
Suppliers receive cash against deliveries and contracts. Utilities and infrastructure developers can negotiate long-term commitments; equipment makers can earn profits before the final end-user market settles. That is not evidence of improper conduct. It is a normal but uneven allocation of risk across a capital-investment chain. Cloud customers may benefit from capacity being offered aggressively to win market share, yet those discounts are not guaranteed to persist if financing conditions tighten.
At the financing layer, owners of newly issued shares provide equity capital while bond investors supply debt. Dividend and buyback decisions become distributional decisions when spending is very large. In a diversified retirement fund the exposure may be indirect, but a market-cap-weighted index increases its allocation to firms that have already become very large. The effect of a sudden repricing on a specific household depends on the fund's holdings and the investor's time horizon, neither of which can be inferred from a single stock chart.
The deeper issue is technology and digital infrastructure investment (opens in a new tab): whether investment increases productivity and welfare more quickly than it absorbs resources. A data centre is an asset, not automatically a benefit to the public. The test is what valuable services it enables, at what cost and to whom.
06 Narrative vs record
A simple bearish story says the company is destroying cash to defend a threatened search monopoly. The documents support a narrower proposition: free cash flow was negative in two consecutive quarters; planned capital expenditure is extraordinarily high; search advertising growth underperformed expectations. They do not establish that Alphabet is unable to finance the programme or that AI Mode will permanently destroy ad economics.
A simple bullish story says cloud revenue has doubled, so the investment has paid for itself. The record supports growth in cloud sales and operating profit, but those figures are not a return-on-invested-capital calculation for a particular generation of AI infrastructure. Depreciation schedules, work-in-progress, financing costs and cash conversion matter. Even an extremely successful product can be a poor investment if built at an excessive price or if rivals force prices down.
The market supplied a third story: despite most stocks rising on 29 October, one mega-cap's fall pulled the S&P 500 lower. AP reported (opens in a new tab) the index dropped 0.3% while roughly four-fifths of constituent stocks advanced. This demonstrates index concentration in market behaviour, not that the selloff permanently reduced the economy's productive capacity.
07 Who profits / who pays
| Actor | Gains / loses | Evidence | Label |
|---|---|---|---|
| Chip, equipment and data-centre suppliers | Can earn revenue from investment commitments before final AI returns are known | Filed capex and sector spending reports | STRONG INDICATION |
| Alphabet shareholders and equity-fund savers | Bear mark-to-market losses, dilution risk and the wait for returns | SEC equity issuance; AP price action | PROVEN |
| Alphabet creditors | Hold interest-bearing claims, subject to issuer credit risk | SEC senior-note disclosure | PROVEN |
| Cloud customers | May obtain more capacity and competitive pricing, but long-run pricing remains uncertain | Cloud revenue and backlog; competition inference | HYPOTHESIS |
| Workers in affected functions | Could face changes to hiring and work organisation; no specific layoff proven by this event | Economic transmission inference | HYPOTHESIS |
| Search advertisers | Could gain better targeting or face weaker traditional click pathways | Reuters account of AI Mode monetisation | STRONG INDICATION |
Who pays is not equivalent to who caused the shock. A pension saver buying an index fund did not decide Alphabet's budget, yet may inherit exposure to it. Suppliers receive money for goods and services, but that does not establish excess profit. The benefit to consumers depends on product quality, pricing and the competitive structure that emerges.
08 Strongest countercase
The strongest defence of Alphabet's decision is that falling behind in compute could be the far more expensive error. Google Cloud's 103% reported revenue growth and substantial backlog show that the company is not building solely on a speculative hope that demand might someday appear. The company also develops proprietary TPUs, allowing it to contest the cost structure of its own infrastructure. Managers investing for multiple years should not be judged as if they must generate positive free cash flow every quarter.
This countercase deserves substantial weight. The company reported positive operating income and net income; its filing showed sizable liquid assets and positive trailing annual free cash flow. Neither bankruptcy language nor blanket claims that all the money has been wasted are defensible. The unresolved question is narrower and more demanding: at what utilisation and price does the incremental investment earn more than its cost of capital, after maintenance, power, depreciation and financing?
For a reader, this means avoiding two easy errors. A 12.6% stock fall does not independently measure lost productive value; it measures a sudden change in expectations. Equally, a doubling of cloud sales does not prove that every incremental dollar of expenditure was well allocated.
09 What would change the verdict
This assessment would improve if Alphabet disclosed a sustained recovery in free cash flow while maintaining cloud growth, stable or improving search monetisation and acceptable returns on new clusters. Repeated quarters showing conversion of cloud backlog into cash, higher utilisation of deployed systems and less need to issue equity would be persuasive. A breakdown of AI Mode advertising yield relative to conventional search would clarify whether the existing franchise is being enhanced or partly displaced.
It would deteriorate if capital spending keeps accelerating while operating cash fails to follow; if the cloud backlog is cancelled or repriced; if depreciation starts materially outrunning economic returns; or if search advertising growth continues to slow despite higher AI engagement. None of those developments is established merely by the events of 29 October.
The indicator chain is explicit: AI capex drives the AI race and compute concentration; equity repricing changes retirement-portfolio wealth and the concentration of large-company indices; a shift toward government bonds can lower Treasury yields and potentially affect borrowing benchmarks. The labour-market channel is less direct: productivity and automation can weaken demand for some roles while infrastructure construction strengthens demand for others through labour-market tightness (opens in a new tab). Better retirement outcomes and affordable services would indicate net public benefit; lost savings or more expensive essential services would point the other way.
For a future indicator entry, track the share of the S&P 500 market capitalisation represented by its largest AI-exposed constituents, alongside the US ten-year Treasury yield and realised household retirement-asset exposure. No new live Factrail indicator link should be fabricated for this proposal. The central lesson is that impressive AI capacity is a productive asset only when somebody ultimately pays enough for its use.
10 Evidence file
- Alphabet — Third Quarter 2026 Results, SEC exhibit (opens in a new tab) — quarterly segment results, operating cash flow, property purchases, free cash flow, equity issuance and notes. Label: PROVEN company disclosure; future forecasts remain management expectations.
- Reuters — Alphabet stock sinks as search woes cause revenue miss (opens in a new tab) — analyst comparisons, management statements and cloud backlog. Label: REPORTED.
- Associated Press — A historic drop for Alphabet drags markets lower (opens in a new tab) — 29 October market action and index breadth. Label: REPORTED.
- Yahoo Finance — Alphabet loses $475 billion in market value (opens in a new tab) — alternative market-cap estimate. Label: REPORTED.
- 9to5Google — Alphabet reports Q3 revenue of $127.6 billion (opens in a new tab) — independent accessible earnings recap. Label: REPORTED.
- Yahoo Finance — Alphabet's worst day and the valuation of search (opens in a new tab) — price change and analyst valuation arguments. Label: REPORTED; valuation is opinion, not audited fact.
- Euronext / Reuters — Stocks fall on AI cash-burn worries (opens in a new tab) — contemporaneous cross-asset market context. Label: REPORTED.
Evidence
The sources this article cites, claim-bearing material first.
More analysis
Ranked by shared facts, drivers and people — never by publication date alone.
Articles12
- Paducah's $100bn AI Campus Faces Power-Bill TestShares the driver: Concentration of AI Compute Resources · 2 November 2026
- The FTC's Cintas–UniFirst Review Tests Uniform-Service CompetitionShares the driver: Labour-Market Tightness · 28 October 2026
- The Concentration of Computing Resources: Who Controls the Development of AI?Shares the driver: Concentration of AI Compute Resources · 3 August 2026
- The Labour Market after COVID-19: Worker Shortages, Remote Work, and New ExpectationsShares the driver: Labour-Market Tightness · 3 August 2026