Trump Made Opportunity Zones Permanent. Governors Pick the Winners Before Washington Can Measure the Results.
By the Factrail desk · Method: how we source and score · Last reviewed
TL;DR
The legal change forms part of Donald Trump's policy record; implementation and federal revenue effects require examination of Scott Bessent's Treasury role and [fiscal-policy sustainability](https://factrail.a...
Key graph impact
The article explains graph entities; the causal edges belong to the facts and drivers it links to.
- ArticleTrump Made Opportunity Zones Permanent. Governors Pick the Winners Before Washington Can Measure the Results.
- mentionsDriverFiscal-Policy Sustainability
Article
The legal change forms part of Donald Trump's policy record (opens in a new tab); implementation and federal revenue effects require examination of Scott Bessent's Treasury role (opens in a new tab) and fiscal-policy sustainability (opens in a new tab), rather than assuming real-estate investment delivers a net public return.
Factrail investigation and documentary analysis | 1 November 2026 | United States
The finding. Congress and President Donald Trump made the Opportunity Zone capital-gains tax incentive permanent in July 2025, then gave state governors another opportunity to choose the census tracts where qualifying investors could obtain favorable federal tax treatment. In April 2026, Treasury identified 25,332 initially eligible low-income tracts, including 8,334 classified as entirely rural. In August, the Government Accountability Office reported that qualified funds already held more than $108 billion in assets at the end of 2024, yet states generally could not say what the original program had achieved for residents. By October, Republican Governor Greg Abbott had nominated 608 Texas tracts and Democratic Governor Bob Ferguson had nominated 99 in Washington. The legally identifiable winners are eligible investors receiving conditional tax benefits, not every resident of a selected neighborhood. No record reviewed proves a governor selected a tract to enrich a donor or that any named politician personally profited.
A tax preference became a permanent map-making power
The central document is Public Law 119-21 and its implementation as examined by GAO (opens in a new tab). The 2017 Tax Cuts and Jobs Act established Opportunity Zones as a way to draw private capital into low-income communities. Taxpayers realizing capital gains could reinvest through a Qualified Opportunity Fund, defer recognition of eligible gains and potentially exclude appreciation on a qualifying long-held investment. That structure makes the investor the direct recipient of the federal tax advantage. The development project and surrounding community may benefit too, but those effects are separate propositions that need evidence.
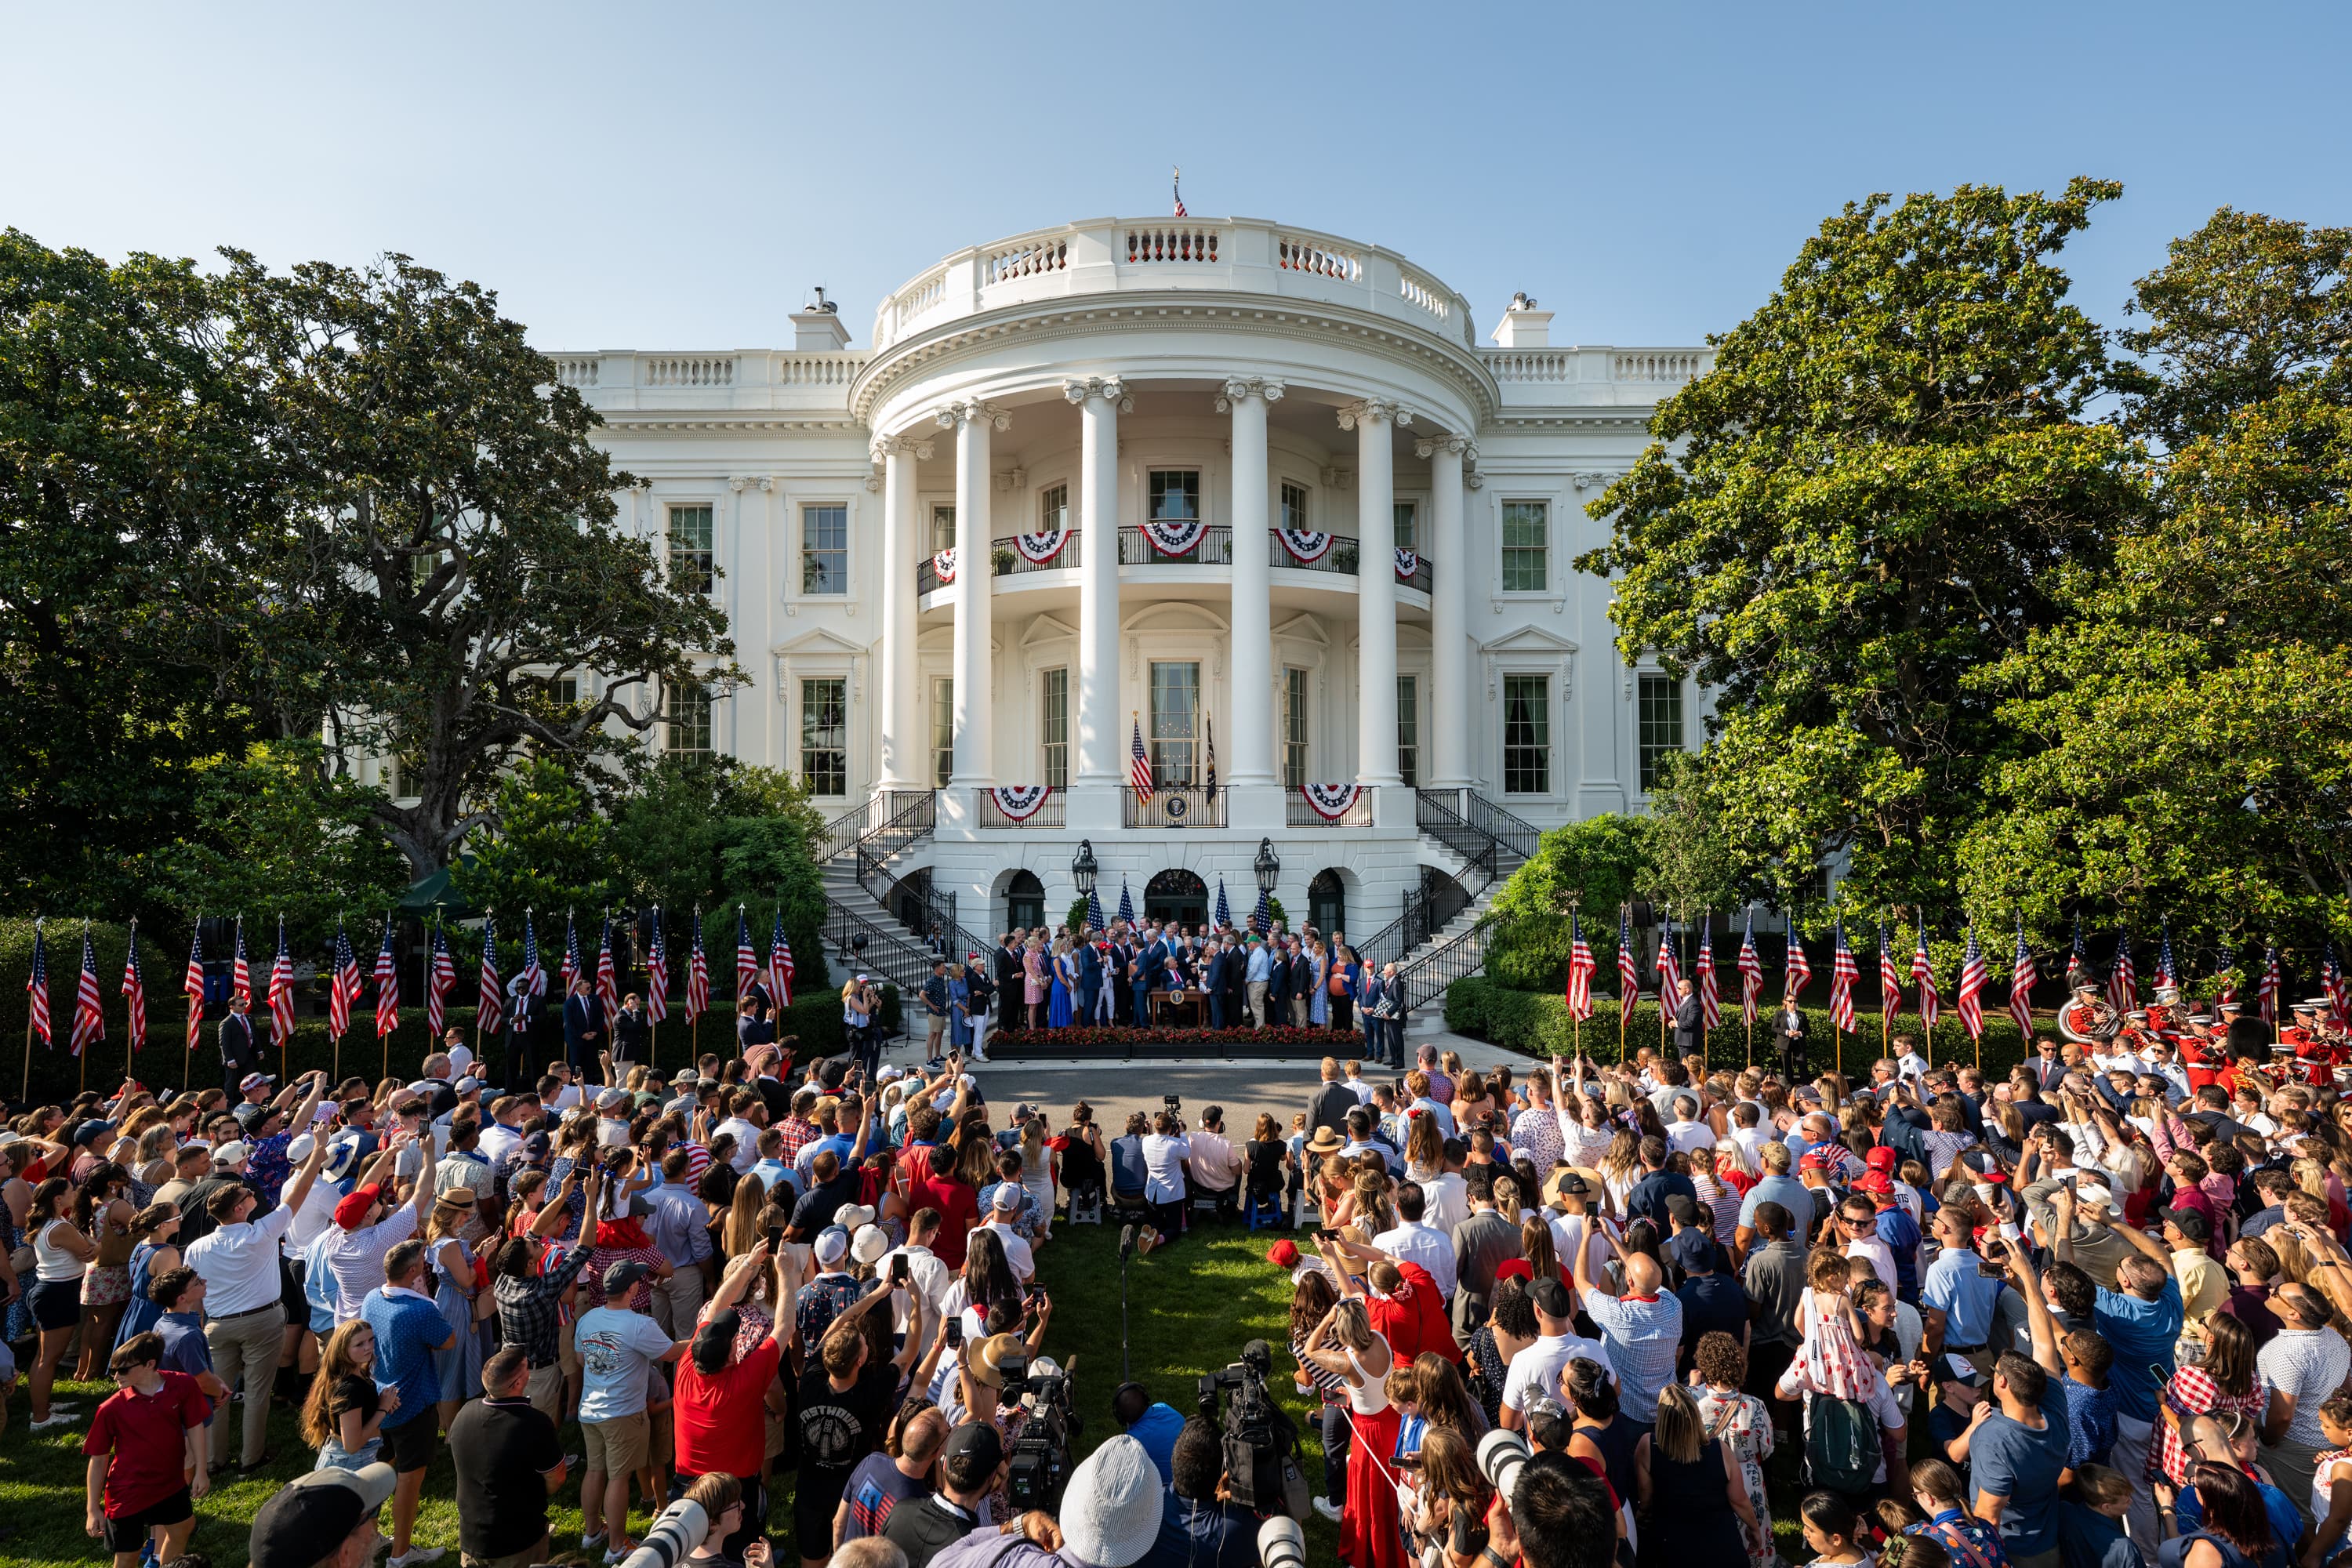
Trump signed the 2025 tax law on July 4. It made the incentive permanent and introduced ten-year rounds of designations, with the next map effective January 1, 2027. It also created enhanced treatment for qualifying rural investments. The law was a congressional decision, not an executive order unilaterally issued by Trump. Congress determined the statutory benefit and eligibility conditions; governors nominate eligible census tracts; Treasury certifies the nominations under the legal procedure; the IRS administers taxpayer compliance. Those are distinct authorities, with different points at which a decision can be questioned.
This arrangement makes geographic designation an unusually consequential political choice. An otherwise eligible parcel on one side of a census-tract boundary can qualify for a valuable tax framework while a similar project outside a designated tract cannot. The governor does not sign a private investor's tax return, set the return on a particular building or compel anyone to invest. The governor does, however, influence the menu of places where qualifying investments may receive the incentive. Treasury's federal eligibility screen limits that choice, and the statute caps the number of tracts that can be selected.
The IRS guidance issued April 6, 2026 (opens in a new tab) initially identified 25,332 eligible low-income tracts, 8,334 of them entirely rural. States generally could nominate up to one quarter of their eligible tracts, with special rules for jurisdictions with fewer than 100. The original nomination period opened July 1 for 90 days, subject to a single 30-day extension. The government later refined some eligibility information; the April figure should not be presented as a final count of approved 2027 zones. Nor is nomination equivalent to Treasury certification.
Documentary timeline: the law moved faster than its evidence
In 2017, Congress created the original tax preference. In 2018, governors chose the first map, eventually covering nearly 9,000 tracts. In October 2021, GAO warned that the IRS lacked readily usable data to assess compliance risks and that wealthy investors and large partnerships required particular attention. The 2021 GAO report (opens in a new tab) subsequently recorded some corrective work, including an IRS identifier to track taxpayers with multiple fund investments. That improvement matters: not every earlier weakness remained wholly unaddressed.
In July 2025, Congress renewed the policy permanently. Independent analysts immediately identified a central tension: investors could gain a more predictable, longer-lived incentive, while the public still lacked complete tract-level outcome information. David Wessel's Brookings analysis (opens in a new tab) explained that the law tightened eligibility, added rural benefits and introduced reporting requirements that the original 2017 framework had not included. The reform is real, but it does not retroactively supply missing evidence about earlier investments.
The next step was operational. In April 2026, Treasury and IRS published the initial eligibility and nomination procedure. Treasury Secretary Scott Bessent argued in the agency's announcement that permanent renewal offered long-term certainty for investors and communities. That is the administration's stated rationale, not proof of measured community gains. On August 24, GAO published its new assessment, based on census data, a state survey, interviews and a nongeneralizable sample of 16 funds. It found that the incentive appeared to favor real estate, often in urban places already equipped with infrastructure and local support. Most states could not reliably describe overall effects on residents.
Then came the state choices. On September 4, according to the Texas governor's official Opportunity Zones page (opens in a new tab), Abbott's office submitted 608 tracts across 106 counties. The office says it solicited proposals from economic-development organizations and county judges and considered eligibility, local support, project viability and geographic balance. On October 8, Ferguson's Washington announcement (opens in a new tab) identified 99 nominations across 27 counties and 17 tribal lands, selected from 152 applications; 36 of the nominations represented rural communities. These two governors belong to different parties, yet both exercised the same federally delegated gatekeeping role.
The federal designation process is still consequential after nomination. A governor's press release is evidence of a submission, not evidence that every tract was certified or that capital has reached it. The new map is intended to take effect in January 2027. A definitive comparison of the chosen places and actual investment flows requires Treasury's certified list and subsequent taxpayer reporting.
Where the money is, and where it is not
The most easily abused number in this story is $108 billion. GAO reports that Qualified Opportunity Funds held more than that amount in assets at the end of 2024. This is a stock of fund assets, not the annual cost of the federal tax preference, not a Treasury grant, not a single-year investment flow and not an estimate of gains to investors. It cannot be converted into a dollar-for-dollar taxpayer loss. To calculate the fiscal cost, an analyst would need actual tax liabilities, timing, counterfactual behavior, appreciation and compliance records. None of those quantities can be inferred from the fund asset total alone.
The benefit mechanism is nevertheless clear. First, a taxpayer has an eligible capital gain. Second, the taxpayer puts qualifying money into a fund that must comply with statutory asset and location rules. Third, the investment can receive favorable tax timing and, if held long enough and other conditions are met, favorable treatment of appreciation. The revised rural framework offers an enhanced basis adjustment after five years compared with standard investments. A rural project can also face a lower threshold for substantial improvements to existing property. These features can change which project a developer considers financially attractive. They do not guarantee that the project will open, hire local residents or lower housing costs.
Real estate has a structural advantage. A building can be located and valued in a designated tract; its holding period can fit a long-term capital-gains strategy; and a developer can combine the tax preference with local abatements, housing subsidies or other incentives. GAO's interviews found that selected funds sometimes combined incentives to make projects viable. That means a finished development may have several public supports, and attributing the whole building to the Opportunity Zone provision would overstate the program's contribution.
The immediate named institutional beneficiaries are Qualified Opportunity Funds and qualifying investors as classes. Specific funds can receive investment and developers can earn fees or project returns, but the examined federal audit does not provide a complete public roster of their ultimate owners or individual tax savings. A named governor's nomination is not evidence of a payment to that governor. The public-interest concern is the design of a geographically targeted tax expenditure whose private benefit can be legally realized without a demonstrated corresponding benefit to original residents.
Texas and Washington: different politics, similar veto points
Texas offers a relatively explicit account of its screening logic. Abbott's office says the Economic Development and Tourism Office invited local nominations and assessed whether private capital could realistically be deployed within 24 to 48 months. That criterion is understandable if the goal is to generate actual construction. It also creates a selection tension: the places most attractive to investors may not be the places with the deepest deprivation or least access to capital. The Texas submission of 608 tracts is a state nomination count, not 608 funded projects.
Washington's process provides a different transparency test. Ferguson says the state consulted the public, business leaders and federally recognized tribes, and selected 99 tracts from 152 applications. The published examples include existing or proposed housing developments, including the Koz on MLK project in Tacoma and Peyton Lofts in Spokane. The announcement is useful evidence of the administration's priorities and examples, but the project descriptions are not a controlled measurement of how much of each outcome was caused by the federal tax preference. Nor does a development's presence in an original zone prove that it is included in the new map.
These two cases show the power path without presuming improper conduct. Local developers and civic organizations may lobby or advocate for particular tracts; state agencies assess applications; governors nominate; Treasury determines legal eligibility and certification; investors make independent decisions; and IRS compliance occurs later. To prove favoritism, an investigation would need tract-level selection files, contacts and meetings, comparative scoring, ownership and donation records, and evidence connecting a specific intervention to a decision. None of those links has been established here. The absence of that proof must not be replaced by insinuation.
The measurement problem is not just missing paperwork
GAO's August report provides an unusually direct measure of uncertainty. Its survey covered the 50 states, Washington, D.C., and five territories; 54 of 56 responded in 2025. Among states reporting awareness of Opportunity Zone investment, some identified jobs or housing as benefits, but the survey does not constitute a national causal evaluation. GAO said about one fifth of states cited increased job creation and housing, while most were uncertain about the overall results. A state official's impression is useful context, not a reliable count of residents whose incomes increased because of the tax break.
GAO's sample of 16 funds likewise cannot be projected to the whole industry. It did find actual progress: by June 2026, 12 of the selected funds had completed development of all projects that had been planned at the time of GAO's earlier review; two had completed some, one had abandoned one project while continuing another, and one was no longer pursuing the original incentive. That is a counterweight to any suggestion that the incentive produced nothing. Completion, however, is not the same as a demonstrated net improvement in resident welfare.
Independent economic research asks a sharper question. In a 2025 NBER working paper revised January 2026 (opens in a new tab), Matthew Freedman, Noah Arman Kouchekinia and David Neumark found that Opportunity Zone designation increased job creation inside zones, but much of that gain was offset by declines in nearby low-income communities. Their analysis suggested limited benefits for existing residents and substantial spatial reallocation. The NBER research summary (opens in a new tab) also describes stronger urban than rural employment results. This is a research estimate with methodological limits, not a definitive audit of every fund or every state.
An earlier Journal of Economic Perspectives assessment (opens in a new tab) by Kevin Corinth and Naomi Feldman reached a related caution: the incentive may subsidize investments that would have happened without it, with limited evidence of improved resident wellbeing. Urban Institute researchers Brett Theodos and Brady Meixell (opens in a new tab) argued in May 2025 that investment was heavily concentrated in metropolitan areas and that additional tax incentives alone were unlikely to redirect enough capital to the most neglected places. These studies are independent analytical lineages, but they examine different periods, data and outcomes. Their estimates should not be mechanically combined.
The difference between place and person is crucial. An apartment building can raise the value of land in a census tract while rents rise for existing tenants. A construction project can employ workers commuting from wealthier neighborhoods. A new business can relocate from a nearby distressed tract rather than create net metropolitan employment. Conversely, new housing supply can benefit future tenants, a factory can generate durable jobs, and rehabilitation can remove a derelict property. A serious evaluation must identify the counterfactual, the geographic spillover and the people actually affected.
The strongest case for the 2025 reform
The administration and program advocates have substantive arguments. Investors require predictable rules, and the original incentive's approaching expiration reduced the usefulness of its deferral provision. The new law makes the framework durable and establishes recurring map reviews rather than freezing the first designation choices indefinitely. It narrows eligibility and removes a former rule permitting some adjacent tracts to qualify. It offers enhanced rural benefits and adds reporting obligations. GAO's interviews found that representatives of 11 of 16 selected funds regarded permanence positively; six expressed interest in rural investment. That is evidence of potential changed behavior, though not of completed future investments.
The best pro-reform argument is therefore not that $108 billion has already been shown to lift poor households. It is that a previously opaque program can be better targeted, measured and adjusted. Washington's selection process and Texas's published criteria demonstrate at least some state-level disclosure. IRS data improvements since 2021 also rebut the idea that oversight has been entirely static. The strongest critics should concede those changes.
The counterargument is equally concrete. Fund representatives told GAO that low rural rents, construction costs, higher interest rates and limited local demand may still deter investment even with the larger rural tax benefit. The GAO found that four selected funds did not expect rural incentives to meaningfully change patterns, while other respondents were optimistic. A subsidy can change after-tax returns without changing the underlying demand for housing or business services. There is no basis to call the new rural policy a success or failure before the projects and data exist.
The reporting promise has a built-in limit
Congress added requirements for funds and Treasury to report investment characteristics and local outcomes. Brookings noted that the law calls for information such as amounts invested, employees and residential units. But the GAO explains that taxpayer confidentiality can constrain tract-level public disclosure, particularly where very few investments occur. Thus even improved reporting may not let residents identify every fund owner or compare every project's return. More data will be useful, but a public table of investments is not by itself a causal impact study.
This produces a measurable accountability test for 2027 and later. Publish the final certified tract map and the governor's decision criteria. Record how much qualifying investment actually reaches each area, with lawful confidentiality protections. Separate fund assets, new investment, realized investor tax benefits and public subsidies stacked on the same project. Measure new housing units, affordable units, business starts, net jobs for existing residents, rents, wages and displacement against credible comparable tracts. Distinguish metropolitan relocation from genuinely additional employment. Require changes in the next map if the program repeatedly rewards places already poised to grow.
What the evidence proves—and what would change the finding
The established decision is a permanent federal tax preference with a fresh round of state-controlled nominations. The established financial fact is more than $108 billion in qualified fund assets at the end of 2024, not $108 billion in public spending. The established oversight gap is that the old program's community effects remain incompletely measured despite real investment and some completed projects. The established named political roles are Trump's signature on the 2025 law, Congress's legislation, Bessent's Treasury certification role, Abbott's Texas nominations and Ferguson's Washington nominations. None of these facts establishes corruption or a personal financial conflict.
The decisive missing records are a final national list of certified 2027 zones; tract-by-tract selection justifications; sufficiently granular but lawful fund and investment disclosures; realized tax expenditure data; and credible outcome evaluations for original residents. Evidence that selected projects created additional jobs, affordable housing or businesses that would not otherwise exist would strengthen the reform's case. Evidence of concentrated tax benefits without additional local activity, or of a documented intervention favoring a connected owner, would require a sharper accountability finding. Until then, the most defensible verdict is that the government has renewed a significant private tax advantage while only beginning to build the system needed to establish its public return.
Documentary sources
- GAO, Opportunity Zones: Effects of Original Tax Incentive Mostly Unknown and Revised Incentive May Offer Improvements, August 24, 2026 (opens in a new tab).
- IRS, Treasury and IRS Guidance to States for 2027 Opportunity Zone Nominations, April 6, revised April 8, 2026 (opens in a new tab).
- Texas Governor's Office, Federal Opportunity Zones in Texas, 2026 (opens in a new tab).
- Washington Governor, Ferguson Selects 99 Opportunity Zones, October 8, 2026 (opens in a new tab).
- GAO, Opportunity Zones: Census Tract Designations, Investment Activities, and IRS Challenges, 2021 (opens in a new tab).
- David Wessel, Brookings, How Did the One Big Beautiful Bill Act Change Opportunity Zones?, July 8, 2025 (opens in a new tab).
- Freedman, Kouchekinia and Neumark, NBER, Understanding the Employment Effects of Opportunity Zones, December 2025, revised January 2026 (opens in a new tab).
- Corinth and Feldman, Journal of Economic Perspectives, Are Opportunity Zones an Effective Place-Based Policy?, 2024 (opens in a new tab).
- Theodos and Meixell, Urban Institute, Opportunity Zones Need to Be Retooled to Achieve Impact, May 12, 2025 (opens in a new tab).
No interview, right-of-reply request, tax-return inspection, donor investigation, independent legal review or site publication is claimed.
Evidence
The sources this article cites, claim-bearing material first.
- files.gao.gov · files.gao.gov/reports/GAO-26-108132/index.html
- irs.gov · irs.gov/newsroom/treasury-irs-provide-guidance-to-states-for-nominating-census-tracts-as-qualified-opportunity-zones-under-the-one-big-beautiful-bill
- gao.gov · gao.gov/products/gao-22-104019
- governor.wa.gov · governor.wa.gov/news/2026/governor-ferguson-selects-99-opportunity-zones-encourage-private-investment
More analysis
Ranked by shared facts, drivers and people — never by publication date alone.
Articles12
- Congress Funded $1.625bn to Counter China's Influence. Washington Still Cannot Show What Worked.Shares the driver: Fiscal-Policy Sustainability · 1 November 2026
- GSA Claims $1.68bn in OneGov Savings. It Rejected Auditors' Call for Cloud-Cost Reporting.Shares the driver: Fiscal-Policy Sustainability · 1 November 2026
- Treasury Protected $289 Million for Community Lenders. Court Records Show the Money Still Had to Move.Shares the driver: Fiscal-Policy Sustainability · 1 November 2026
- Trump's Federal Building Sales Have a Data Blind Spot: 20.2 Million Vacant Square Feet Missing From Congress's Occupancy PictureShares the driver: Fiscal-Policy Sustainability · 2 November 2026